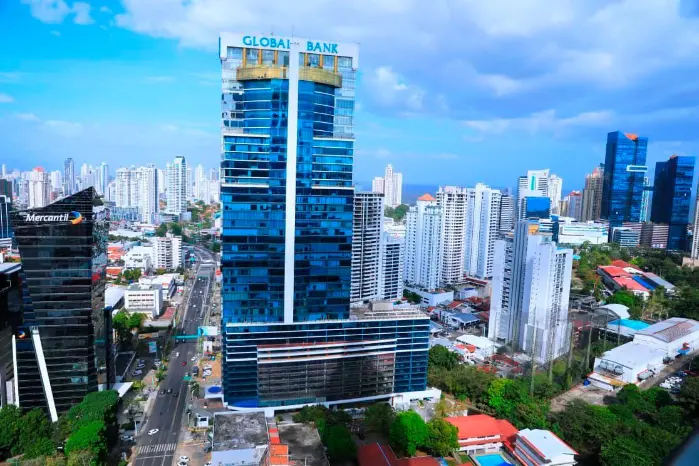
The financial system in Panama has demonstrated remarkable strength and resilience. Key institutions within the International Banking Center (CBI) closed the third quarter with exceptional indicators. Furthermore, prudent monetary management and steady deposit inflows outpaced credit expansion, creating a stable economic foundation across the country.
Additionally, national financial institutions maintained high levels of capital adequacy. Consequently, banking assets grew significantly while overall leverage decreased. These metrics highlight the profound robustness of the national financial system and its capacity to manage global economic fluctuations effectively.
Growth in Bank Liquidity and Solvency
Legal liquidity indicators for the national banking system advanced significantly, reaching 55.33%. This performance maintains a comfortable margin well above regulatory requirements. Furthermore, capitalization ratios doubled the legally mandated minimums, reflecting conservative risk management and prudent balance sheet practices.
Moreover, institutional reserves climbed steadily to absorb potential credit risks. Because of these proactive measures, financial solvency remains exceptionally strong. Stakeholders benefit from transparent reporting and strict regulatory oversight provided by local authorities.
Expansion of Correspondent Banking Networks
International relations have flourished following significant regulatory achievements. Specifically, the removal of Panama from international grey lists enhanced global perception and trust. Consequently, the count of active correspondent banks increased from 431 to 435 over a twelve-month period.
This expanded network facilitates seamless cross-border transactions and enhances international trade financing. Furthermore, global financial institutions view the local regulatory framework with renewed confidence, ensuring smoother operations for international investors and corporate clients alike.
Deposit Growth and Credit Dynamics
Deposits emerged as the primary catalyst for overall financial expansion. Private sector deposits grew robustly, accounting for the vast majority of capital inflows. Meanwhile, credit placement in key economic sectors maintained a steady, manageable pace.
Ultimately, these combined factors reduced the net credit-to-deposit ratio, ensuring sustainable long-term growth. The financial sector continues to support national economic development while preserving high standards of compliance and risk mitigation.